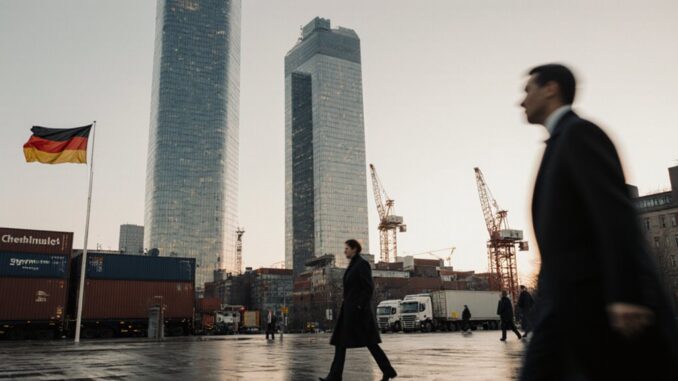
Germany is expected to post modest, uneven growth as weak manufacturing orders, soft Chinese demand, high energy costs, and skilled-labor shortages constrain output. Inflation is moving toward the ECB’s 2% target, supporting gradual rate cuts, though financing will remain selective. Exporters face trade-policy, supply-chain, and currency risks, while decarbonization rules raise compliance demands. Targeted incentives may support energy, digital, and industrial investment. The factors below outline the key risks and opportunities.
Germany’s Economic Outlook: Growth, Risks, Opportunities
Germany’s economy is expected to return to modest growth after a prolonged period of weak industrial output, subdued domestic demand, and high energy costs, but its recovery remains uneven. Export-oriented manufacturers remain exposed to softer Chinese demand, trade fragmentation, and supply-chain volatility, while skilled-labor shortages constrain capacity in engineering, construction, and digital services.
Opportunities are concentrated in sectors supported by industrial policy and European strategic priorities. Aerospace investment, defense procurement, renewable-energy deployment, semiconductor capacity, and electrification could strengthen supplier networks and attract foreign partnerships. Modernizing logistics infrastructure—particularly rail freight corridors, ports, grid connections, and digital customs systems—would improve competitiveness for internationally integrated businesses.
Key risks include regulatory complexity, delayed planning approvals, elevated input costs, and uncertainty over coalition policy implementation. Companies entering or expanding in Germany should assess regional incentives, energy-security exposure, workforce availability, and compliance requirements. Diversified sourcing and local partnerships can reduce operational vulnerabilities while positioning firms for long-term industrial renewal.
Growth, Inflation, and Interest Rate Outlook
Although growth is expected to improve gradually, Germany is likely to remain among the euro area’s slower-growing major economies as weak external demand, high financing costs, and structural capacity constraints limit momentum. Export-oriented manufacturers remain exposed to softer Chinese demand, uneven global trade, and geopolitical market volatility. Household spending should strengthen only modestly as real wages recover, while consumer confidence remains below levels consistent with a broad consumption-led expansion.
Inflation is expected to move closer to the European Central Bank’s 2% target, although services prices, wage settlements, and administered costs may slow disinflation. This outlook supports a cautious ECB easing cycle rather than a rapid return to exceptionally low borrowing costs. For international businesses, financing conditions should improve incrementally, but credit availability may remain selective, particularly for smaller firms and property-linked activities. Fiscal policy constraints and coalition-level budget decisions could further shape domestic demand, public investment, and business sentiment through 2025 and beyond.
Energy Costs, Green Rules, and Incentives
Energy remains a central competitiveness issue for internationally exposed firms, as German industrial electricity and gas prices have eased from their 2022–23 peaks but generally remain above pre-crisis levels and often exceed those faced by competitors in the United States, China, and parts of the Middle East. This gap is especially relevant for chemicals, metals, glass, paper, and data-intensive operations, where energy prices materially affect location and investment decisions.
Policy support can partly offset costs. Energy-tax relief, grid-fee measures, carbon-contract schemes, and grants for electrification, hydrogen, storage, and efficiency are available, though eligibility and approval timelines vary. Firms should also monitor EU emissions trading, the Carbon Border Adjustment Mechanism, renewable-energy sourcing rules, and German building and supply-chain requirements. Regulatory compliance increasingly requires auditable emissions data, procurement documentation, and credible decarbonization plans. International investors should model energy exposure under multiple price and carbon scenarios, while assessing whether incentives sufficiently compensate for higher operating costs and administrative complexity.
Labor Shortages, Wages, and Hiring Costs
Germany’s skilled-labor shortage is tightening recruitment conditions in engineering, IT, healthcare, and advanced manufacturing, raising competition for qualified workers. Wage growth, social-security contributions, and compliance costs are increasing total hiring expenses relative to some international locations. Immigration policy, vocational training, and labor-market reforms will likely remain material variables for companies planning German expansion.
Skilled Labor Shortages
How severe is Germany’s skilled labor gap? Surveys from chambers of commerce and the Federal Employment Agency consistently show shortages across engineering, information technology, healthcare, construction, and skilled trades. Demographic pressures are central: large cohorts are retiring while fewer young entrants replace them. For international businesses, constraints can delay plant expansion, digital transformation, and service delivery despite otherwise strong demand conditions. Policy responses include faster recognition of foreign qualifications, revised skilled-immigration rules, expanded language support, and efforts to increase labor-force participation among women and older workers. Companies are also strengthening Apprentice programs with schools and vocational institutions to build occupation-specific pipelines. Effective workforce retention increasingly depends on training access, predictable career progression, flexible work arrangements, and integration support for international hires. Regional variation remains significant, with industrial centers and rural areas often facing distinct recruitment challenges.
Rising Wage And Hiring Costs
Tight labor markets are translating directly into higher wage bills and recruitment costs for employers in Germany, particularly in engineering, IT, healthcare, logistics, construction, and skilled trades. Collective agreements, minimum-wage adjustments, and competition for scarce specialists are raising total labor costs beyond base salaries.
- Recruiters bid for software engineers across Berlin, Bangalore, and Boston.
- Hospitals offer signing bonuses to secure nurses and technicians.
- Logistics firms pay premiums for licensed drivers and night shifts.
- Construction sites face delays when certified tradespeople remain unavailable.
- Manufacturers accelerate automation investments to offset vacancies.
International businesses should model wage escalation, payroll taxes, training, and relocation support in market-entry plans. Germany’s immigration reforms may expand talent pipelines, but credential recognition and housing constraints can slow hiring. Firms that pair targeted compensation with productivity gains, reskilling, and workforce planning can protect margins while maintaining capacity amid persistent demographic pressure.
Industrial Output and Manufacturing Demand
Germany’s industrial production remains a key indicator of broader economic momentum, with factory output shaped by energy costs, financing conditions, and sector-specific demand. Manufacturing orders and capacity utilization provide early signals on investment cycles, particularly in autos, machinery, chemicals, and electronics. Export-oriented firms also face pressure from weaker external demand, trade-policy shifts, and intensifying competition in major markets such as China and the United States.
Industrial Production Trends
Germany’s industrial sector remains under pressure as weak external demand, high energy costs, and elevated financing conditions constrain output across key manufacturing categories. Production remains below pre-pandemic levels, with chemicals, metals, and energy-intensive processes facing persistent cost disadvantages. Export-oriented firms also confront slower activity in China and uneven euro-area growth.
- Quiet factory floors reflect reduced capacity utilization.
- Chemical plants operate beneath historical production norms.
- Auto lines adjust to changing supply chain availability.
- Energy bills reshape investment decisions in industrial regions.
- Port containers signal volatile global trade flows.
Policy measures supporting grid expansion, renewable power, and investment incentives could improve competitiveness, but implementation speed remains decisive. For international businesses, pricing signals from energy, freight, and intermediate goods warrant close monitoring, alongside regulatory developments affecting decarbonization and trade.
Manufacturing Demand Signals
Although recent industrial data have shown intermittent monthly gains, Germany’s manufacturing demand remains subdued, with weak new orders, soft export markets, and cautious capital spending limiting a sustained recovery in output. Survey indicators point to uneven order books across machinery, chemicals, automotive supply chains, and energy-intensive industries. Domestic demand has not fully offset the investment restraint caused by elevated financing costs, uncertain energy expenses, and regulatory transformation requirements. The Deutsche Konjunktur thus remains sensitive to changes in credit conditions, public infrastructure spending, and corporate confidence. Exportnachfrage is an important component of factory utilization, but current demand signals also reflect broader global manufacturing cycles rather than a purely domestic slowdown. International businesses should monitor order intake, purchasing-manager surveys, inventory levels, and capital-goods bookings. Faster permitting, targeted energy-cost relief, and predictable industrial policy could improve demand visibility and support production planning.
Export Market Pressures
Weak external demand is amplifying the pressure on German industrial output, particularly in export-oriented sectors such as machinery, vehicles, chemicals, and electrical equipment. Slower orders from China, uneven European recovery, and tighter global financing are reducing factory utilization and investment plans. Currency movements complicate pricing, while trade volatility raises inventory and logistics costs. Policymakers are monitoring whether foreign export subsidies distort competition and restrict fair market access for German producers.
- Idle assembly lines signal softer overseas vehicle demand.
- Chemical plants face weaker orders from Asian construction markets.
- Machinery exporters confront delayed capital-spending decisions worldwide.
- Port containers move more slowly through northern trade gateways.
- Suppliers reassess production schedules amid tariff and shipping uncertainty.
International businesses should track order books, destination-market regulations, and credit conditions. Diversified sales channels and localized partnerships may reduce exposure to concentrated export risks.
Trade Exposure and Geopolitical Risks
As one of the world’s most export-oriented advanced economies, Germany remains highly exposed to shifts in global demand, trade policy, and geopolitical disruption. Manufacturing sectors, including autos, machinery, chemicals, and electrical equipment, depend on predictable access to markets and imported inputs. Slower Chinese growth, trade frictions between major economies, and possible tariff escalation could weaken orders and raise compliance costs for German exporters.
Supply Chain Disruptions remain a material operational risk, particularly where production relies on components from East Asia, critical minerals, or maritime routes through the Red Sea. Energy-security concerns also continue to shape industrial competitiveness following reduced Russian pipeline gas supplies. Firms are increasingly evaluating supplier diversification, inventory buffers, and nearshoring options.
Currency Volatility adds another layer of uncertainty. Although the euro can support export competitiveness when weaker, exchange-rate movements affect imported energy, raw-material costs, and overseas earnings. Businesses should monitor sanctions regimes, export controls, shipping conditions, and evolving EU trade-security measures.
Fiscal Policy, Taxes, and Investment Support
Against this external-risk backdrop, fiscal policy and the tax environment will materially influence Germany’s investment outlook. Budget constraints, including the constitutional debt brake, limit room for broad stimulus even as weak export demand and supply disruptions weigh on industrial output. Policymakers are prioritizing targeted support for decarbonization, semiconductors, energy security, and digital infrastructure, while debate continues over corporate-tax competitiveness and investment allowances.
- Factory rooftops fitted with solar panels and battery storage
- Chip fabrication sites supported by multibillion-euro public incentives
- Rail corridors, bridges, and grids awaiting accelerated capital spending
- Energy-intensive plants seeking relief from elevated electricity costs
- Research laboratories drawing grants for AI, climate, and advanced manufacturing
For international investors, Germany’s appeal rests on predictable institutions, skilled labor, and EU market access, but project economics increasingly depend on subsidy eligibility, permitting speed, and effective tax rates. Federal and state programs can lower upfront costs, although complex administration may delay deployment. Fiscal choices will in turn shape whether private capital offsets subdued domestic demand and supports productivity-enhancing investment.
How Businesses Can Prepare for Germany’s Outlook
International businesses can prepare for Germany’s uneven outlook by stress-testing demand, energy, financing, and supply-chain assumptions against slower industrial activity, shifting trade conditions, and policy changes. Scenario Planning should model weak export demand, volatile electricity costs, tighter credit, and upside cases linked to public investment, defense spending, and digitalization.
Regulatory Readiness is essential as firms navigate evolving EU sustainability reporting, carbon-border requirements, trade controls, subsidy rules, and labor-market obligations. Local legal and compliance teams should translate federal and EU measures into operational timelines and investment decisions.
Treasury Resilience requires diversified funding sources, disciplined working-capital controls, currency hedging, and sensitivity analysis for euro interest rates. Companies with German operations should monitor bank lending standards and supplier liquidity.
Supply Chain Diversification can reduce exposure to single-country inputs and transport disruptions. Dual sourcing, regional inventories, and supplier risk assessments can protect production while preserving access to Germany’s advanced manufacturing base and the wider European market.
The Business & Economy Editorial Team covers Germany’s economy, companies, markets and international trade. Its reporting focuses on economic developments, investment, exports, the Mittelstand, major corporations and the conditions affecting businesses in Germany. The team combines current economic news with background articles and analysis to explain what developments mean for companies, investors and international readers.