Germany became Europe’s largest economy by rebuilding its industrial base after World War II and sustaining an export-led model. Its nominal GDP is near €4.5 trillion, ahead of France, Italy, and Spain. Manufacturing produces about 18% of value added, above the EU average, while skilled workers, Mittelstand suppliers, and global firms support competitiveness. EU single-market access broadens demand across 440 million consumers. These foundations also reveal the pressures shaping Germany’s next economic chapter.
Why Germany Has Europe’s Largest Economy
Germany has Europe’s largest economy because it combines a large industrial base, high-value exports, a skilled workforce, and deep integration into the European Union’s single market. With nominal GDP near €4.5 trillion, Germany exceeds France, Italy, and Spain, giving it roughly one quarter of euro-area output. Manufacturing contributes about one fifth of domestic value added, a larger share than in most major Western European economies, and supports globally recognized strengths in vehicles, machinery, chemicals, electrical equipment, and precision engineering.
Its export orientation broadens demand beyond domestic consumption: goods and services exports account for a substantially higher share of GDP than in France or the United Kingdom. Labor productivity is reinforced by vocational training, specialized suppliers, research capacity, and capital-intensive production. Membership in the EU provides tariff-free access to a market of more than 440 million consumers, while the euro reduces transaction costs across key trading partners. These conditions sustain global competitiveness despite high wages, energy costs, demographic pressures, and intensified competition from China and the United States.
How Postwar Recovery Built Germany’s Economy
West Germany’s postwar recovery combined Marshall Plan assistance with currency reform, market liberalization, and rebuilding of industrial capacity. During the 1950s, the Wirtschaftswunder helped real output expand far faster than in many European peers, supported by exports, investment, and a growing labor force. This industrial resurgence established the manufacturing base that later made Germany Europe’s largest economy.
Marshall Plan Support
Although devastated by war, the western German occupation zones entered the Marshall Plan in 1948 and received roughly $1.4 billion in U.S. aid by 1952, making them one of Europe’s largest recipients. The funding supplied food, fuel, industrial inputs, transport equipment, and credits, easing severe shortages while reducing pressure on limited domestic resources. Aid was substantial, though smaller in absolute terms than some allocations to Britain and France; its importance lay in supporting coordinated Economic rebuilding under conditions of damaged infrastructure and restricted trade. Marshall Plan institutions also required participating states to share information, allocate resources, and lower barriers within the European Recovery Program. For West Germany, this framework connected reconstruction to european integration, restoring commercial links with neighboring economies. U.S. assistance hence functioned less as a standalone solution than as a stabilizing external resource and a mechanism for multilateral economic coordination.
Wirtschaftswunder and Industrial Growth
By the early 1950s, the Federal Republic’s recovery accelerated into the *Wirtschaftswunder*, or “economic miracle,” as industrial production rose rapidly from its postwar low and surpassed prewar levels by 1950. Annual GDP growth averaged roughly 8 percent during the 1950s, exceeding most Western European peers. Currency reform, investment, and expanding labor supply converted reconstruction into sustained industrial capacity.
- Manufacturing output surged in automobiles, chemicals, machinery, and electrical equipment.
- Productivity gains paired with wage restraint strengthened export competitiveness in European and global markets.
- Millions of refugees and later guest workers eased labor shortages and enlarged domestic demand.
Unlike Britain’s slower modernization and France’s more state-directed planning, West Germany combined market institutions with social protections. The Wirtschaftswunder legacy established export-led manufacturing, high employment, and capital formation as enduring foundations of Europe’s largest economy.
How the Mittelstand Powers Germany’s Economy
Germany’s Mittelstand—largely family-owned small and medium-sized firms—employs roughly 60% of the country’s workforce and provides a durable base beyond its largest corporations. Its export-oriented manufacturers anchor specialized supply networks, helping Germany maintain a stronger industrial share of output than many European peers. A dual apprenticeship system supplies these firms with skilled labor, reinforcing productivity, technical expertise, and regional employment.
Family-Owned Business Strength
Unlike economies dominated by large listed corporations, Germany relies heavily on its Mittelstand: roughly 99% of firms are small and medium-sized enterprises, many family-owned and concentrated in specialized manufacturing niches. These businesses provide about 60% of employment and over half of private-sector training positions, anchoring regional labor markets more deeply than comparable firms in France or the United Kingdom.
- Long ownership horizons favor investment in skills, equipment, and product quality.
- Succession planning preserves expertise, governance continuity, and local decision-making across generations.
- Conservative financing and retained earnings support resilience in downturns.
Family control can also limit access to outside capital and delay modernization when leadership transitions fail. Nonetheless, its prevalence reduces dependence on quarterly market expectations. This structure has helped Germany sustain industrial capabilities, specialized employment, and stable regional business ecosystems over decades.
Export-Oriented Manufacturing Networks
Although large multinational brands draw most international attention, Germany’s export performance rests on dense networks of Mittelstand suppliers, machinery makers, and specialized service firms integrated into global value chains. These companies produce precision components, industrial software, chemicals, and equipment that enter vehicles, factories, and infrastructure worldwide. Manufacturing accounted for roughly 18 percent of German gross value added in 2023, well above the shares in France or the United Kingdom, reinforcing export capacity across regions. Long-term Supplier relations allow firms to coordinate design, quality control, and delivery with larger assemblers while retaining technical niches. Germany’s central European location further connects producers to neighboring markets and logistics corridors. This distributed model reduces dependence on a few flagship brands and broadens participation in global trade, though it also exposes smaller exporters to external demand shocks and supply disruptions.
Apprenticeship And Skilled Labor
A dual vocational training system supplies the Mittelstand with technicians, machinists, and industrial specialists whose skills align closely with employer needs. Germany’s dual education model combines classroom instruction with paid workplace training, reducing the gap between qualifications and production requirements. Roughly half of secondary-school leavers enter vocational pathways, a higher share than in many European peers, supporting export industries dependent on precision and reliability.
- Firms shape curricula through chambers of commerce and industry.
- Skilled apprentices gain recognized credentials and early labor-market access.
- Small manufacturers retain specialized know-how across generations.
This system lowers recruitment costs and helps Mittelstand companies adapt machinery, processes, and quality controls quickly. Compared with economies relying more heavily on university graduates, Germany sustains a broader technical workforce, reinforcing productivity in engineering, automotive supply, chemicals, and advanced manufacturing while supporting regional employment stability.
Why Manufacturing Drives Germany’s Economic Strength
Manufacturing sits at the core of Germany’s economic model, contributing roughly 18% of gross value added—well above the European Union average of about 15% and far higher than service-led economies such as France or the United Kingdom. This industrial base supports high productivity, export capacity, and a dense network of suppliers, research institutions, and specialized small and medium-sized firms.
Its strength lies not simply in output volume, but in the integration of engineering, precision production, and applied research. Manufacturing generates substantial demand for skilled labor and helps anchor investment across regions beyond major financial and administrative centers. Compared with economies more dependent on consumption, tourism, or finance, Germany retains greater capacity to produce tradable goods and benefit from global capital investment.
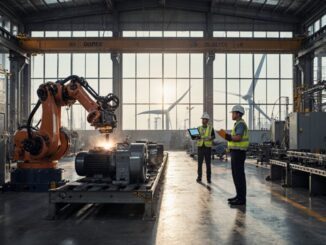
Automation innovation has helped firms raise efficiency while maintaining quality standards amid high wages. Meanwhile, policy and corporate investment increasingly position production within a sustainable industry framework, emphasizing energy efficiency, cleaner processes, and reduced material use.
Germany’s Leading Industrial Sectors and Brands
Germany’s industrial strength is concentrated in globally competitive sectors led by automobiles, machinery, chemicals, electrical equipment, and pharmaceuticals. These industries combine large multinational groups with specialized Mittelstand suppliers, giving Germany a broader manufacturing base than many European peers.
- Automotive leaders including Volkswagen, BMW, Mercedes-Benz, Bosch, and ZF anchor production of vehicles, Car parts, engineering software, and advanced mobility systems.
- Machinery brands such as Siemens, Trumpf, Krones, and DMG Mori supply factory automation, machine tools, industrial equipment, and precision technologies.
- Chemical and pharmaceutical companies, particularly BASF, Bayer, Merck, and Boehringer Ingelheim, support high-value research, materials science, medicines, and laboratory products.
The sectoral mix limits reliance on any single industry. Automotive production remains highly visible, but chemicals and capital goods contribute significant value added and research spending. Compared with economies more dependent on finance, tourism, or consumer services, Germany’s leading brands are embedded in complex industrial supply chains that sustain skilled employment, technical training, and continuous product innovation across regions.
How Exports Power Germany’s Economy
Exports provide a central transmission channel between Germany’s industrial base and global demand: goods and services exports have typically equaled roughly 45–50% of GDP, a far higher share than in larger, more domestically driven economies such as the United States. Machinery, vehicles, chemicals, pharmaceuticals, electrical equipment, and specialized business services supply markets across Europe, North America, and Asia.
This export intensity has supported investment, employment, tax receipts, and productivity by allowing firms to operate at scale beyond the domestic market of 84 million people. Germany’s persistent trade balances, often among Europe’s largest surpluses, reflected strong demand for high-value manufactured products and comparatively restrained imports. Membership in the euro area also reduced currency volatility for trade with neighboring markets. However, dependence on external demand creates exposure to global slowdowns, supply-chain disruptions, energy costs, and competition from China and other producers. Sustaining global competitiveness thus depends on preserving technological leadership while adapting products and export markets to changing demand patterns.
How Vocational Training Supports German Industry
A large share of Germany’s industrial workforce is trained through the dual vocational system, which combines paid apprenticeships in firms with classroom instruction in vocational schools. Each year, roughly 1.2 million apprentices develop occupation-specific skills across manufacturing, engineering, logistics, and technical services. Employers help define curricula, aligning training with production requirements and reducing the mismatch between education and labor demand.
- Apprentices gain practical experience while earning wages, easing school-to-work movement.
- Small and medium-sized manufacturers access a reliable pipeline of machinists, technicians, and mechatronics specialists.
- Standardized qualifications support mobility across regions and preserve quality in specialized trades.
Compared with systems relying more heavily on university degrees, Germany’s model supplies a larger base of intermediate-skilled workers essential to advanced manufacturing. It also enables firms to diffuse Technology innovation through trained shop-floor staff, rather than limiting expertise to engineers. This workforce structure strengthens productivity, limits recruitment costs, and supports global competitiveness in export-oriented sectors such as automobiles, machinery, chemicals, and industrial equipment.
How the European Union Supports Germany’s Economy
Within the European Union’s single market, German firms gain tariff-free access to 26 neighboring economies and a consumer base of roughly 450 million people. This trade access strengthens export-oriented sectors, including vehicles, machinery, chemicals, and electrical equipment, by reducing border costs, harmonizing standards, and simplifying cross-border supply chains. Germany benefits disproportionately from this scale because its manufacturing base is deeply integrated with suppliers and customers across Central and Eastern Europe.
EU budget support also channels funds toward transport links, research, digital infrastructure, and regional development. Although Germany is a major net contributor to the EU budget, structural cohesion spending in less affluent member states expands demand for German capital goods and improves production networks serving German companies. Common rules on competition, procurement, and product safety provide predictable operating conditions across member markets. In addition, EU-level investment promotion, including financing through the European Investment Bank, supports industrial modernization and innovation. Compared with fragmented national markets, the EU gives Germany a substantially larger, more standardized commercial platform.
Challenges Facing Germany’s Economic Future
Germany’s economic model faces a more difficult environment than it did during the export-led expansion of the 2000s and 2010s. Slower global trade, China’s rise as a manufacturing competitor, and weaker industrial output have narrowed advantages once anchored in autos, machinery, and chemicals. GDP growth has lagged both the euro-area average and the United States in recent years.
- Demographic pressures are intensifying: Germany’s working-age population is projected to decline sharply by the 2030s, constraining labor supply and pension financing despite immigration.
- Energy transition costs remain high after the nuclear exit and reduced Russian gas supplies. Industrial electricity prices have generally exceeded those in the United States and China, challenging energy-intensive producers.
- Investment gaps in rail, digital networks, housing, and defense limit productivity. Germany’s public investment has historically trailed several northern European peers.
Fiscal rules restrict borrowing flexibility, while political fragmentation complicates reforms. Maintaining competitiveness will depend on faster permitting, workforce participation, innovation, and more reliable low-carbon energy.
The Business & Economy Editorial Team covers Germany’s economy, companies, markets and international trade. Its reporting focuses on economic developments, investment, exports, the Mittelstand, major corporations and the conditions affecting businesses in Germany. The team combines current economic news with background articles and analysis to explain what developments mean for companies, investors and international readers.