Exchange-rate movements affect German exporters through foreign-currency prices, euro revenues, margins, and competitiveness. A stronger euro typically makes euro-priced goods costlier abroad, potentially reducing demand and compressing margins; a weaker euro can improve price competitiveness in non-euro markets. Effects vary by invoicing currency, contract length, import costs, and pricing power. Automotive, machinery, chemicals, and capital goods face notable exposure. Forward hedges, currency clauses, and natural offsets can limit risk. The following sections explain these channels by sector and strategy.
How Exchange Rates Affect German Export Prices
Exchange-rate movements directly influence the foreign-currency prices of German exports, particularly for goods invoiced in euros. When the euro changes against a buyer’s currency, the invoice value translated into local currency adjusts unless exporters alter euro list prices or use hedging arrangements. The degree of Euro Pass Through depends on contract duration, currency invoicing, competitive conditions, and firms’ capacity to absorb margin changes.
Pricing Elasticity differs across sectors. Specialized machinery, pharmaceuticals, and premium automobiles may sustain relatively stable euro prices because product differentiation limits substitution. Standardized intermediate goods and consumer products typically face stronger competitive pressure, encouraging suppliers to revise prices or offer discounts. Evidence from trade studies generally indicates incomplete pass-through: exporters often distribute exchange-rate effects between foreign buyers and profit margins.
Policy conditions also matter. Stable inflation, predictable monetary policy, and efficient export-credit instruments can reduce pricing uncertainty. Firms with diversified markets and local distribution networks can adjust prices more selectively, limiting abrupt changes in customer-facing costs.
What Happens When the Euro Strengthens?
A strengthening euro raises the foreign-currency cost of German goods priced in euros, potentially weakening demand in markets where buyers are sensitive to price differences. The scale of the effect depends on Euro demand elasticity, contract terms, competitive conditions, and firms’ ability to absorb exchange-rate movements through lower euro margins. Exporters of standardized machinery, vehicles, and chemicals may face greater substitution toward domestic or third-country suppliers when price gaps widen.
A stronger currency can also reduce imported input costs, partly offsetting revenue pressure. The degree of import cost pass through determines whether cheaper energy, components, and raw materials improve margins or are reflected in lower export prices. Large multinational firms may hedge currency exposure or adjust production sourcing, while smaller suppliers often have less flexibility. Policymakers monitor export orders, manufacturing output, and destination-market price indices to assess whether appreciation is creating persistent competitiveness losses, particularly outside the euro area.
What Happens When the Euro Weakens?
Conversely, a weaker euro lowers the foreign-currency price of German exports when euro-denominated prices are unchanged, improving price competitiveness in non-euro-area markets. The effect is most visible in sectors facing close international substitutes, including machinery, vehicles, chemicals, and capital equipment. A 10 percent depreciation, for example, can reduce dollar- or sterling-denominated list prices by roughly 10 percent if firms fully pass through the exchange-rate movement.
Demand responses depend on contract terms, local competition, import regulations, and the sensitivity of buyers to price changes. Export volumes may rise with a lag, particularly where procurement cycles are lengthy. Policymakers therefore monitor exchange-rate developments alongside foreign demand indicators, order books, and trade balances rather than treating depreciation as an automatic stimulus.
Euro translation of overseas sales can increase reported euro revenues when foreign-currency receipts are converted. These accounting effects may improve headline export statistics without demonstrating equivalent growth in physical shipment volumes, requiring careful interpretation of nominal trade data.
How Exchange Rates Affect Export Margins
Exchange-rate movements affect exporters’ margins by changing foreign-currency pricing, euro-denominated revenues, and the cost of imported inputs. Margin compression can arise when firms absorb currency shifts to preserve market share, particularly in contracts with limited repricing flexibility. Hedging through forwards, options, and currency matching can reduce earnings volatility, while policy conditions influence the cost and availability of these instruments.
Currency Movements and Pricing
For German exporters, currency movements directly shape the euro value of foreign sales and the competitiveness of prices quoted abroad. When the euro appreciates against the dollar, sterling, or renminbi, unchanged foreign-currency prices translate into fewer euros, while buyers may face relatively higher prices if firms adjust quotations. The scale of this effect depends on pass through pricing, product differentiation, and local market competition. Exporters using euro invoicing retain clearer revenue certainty but may shift exchange-rate exposure to customers, potentially weakening demand. Where the contract currency is the buyer’s currency, exporters typically monitor exchange-rate thresholds when setting catalogues, tenders, and renewal terms. Policymakers consequently track effective exchange rates alongside export-order data, since broad euro appreciation can reduce price competitiveness unevenly across sectors, destinations, and firms with differing pricing power.
Margin Compression Risks
Pricing decisions determine revenue exposure, but exchange-rate movements ultimately affect whether foreign sales remain profitable after euro-denominated costs are covered. When the euro appreciates, foreign-currency receipts convert into fewer euros, compressing gross margins unless prices rise proportionately. For manufacturers with high domestic wage, energy, and component costs, even modest currency shifts can erase profit on fixed-price orders. Margin sensitivity depends on invoicing currency, production location, import content, and the duration between quotation and delivery. Pricing tactics such as market-specific price adjustments may preserve margins, but competitive conditions often limit pass-through. Contract clauses covering currency adjustment, price revision, or delivery timing can reduce disputes and clarify commercial responsibilities. Policymakers monitoring export competitiveness should thus assess profitability indicators, not export volumes alone, since stable shipment values can conceal declining returns and weakened investment capacity.
Hedging Strategies for Stability
Hedging instruments can stabilize German exporters’ euro margins by reducing uncertainty between the date a foreign-currency contract is signed and the date payment is received. Forward contracts lock in exchange rates, while options preserve upside potential when the euro weakens, albeit at a premium. Firms can align hedge maturities with invoicing schedules and expected cash flows to limit basis and rollover risk.
Policy discipline matters: treasury teams should set hedge ratios by currency exposure, customer concentration, and forecast reliability. Scenario planning can test margin outcomes under defined euro appreciation shocks, helping management establish risk limits and liquidity buffers. Contract clauses, including currency-adjustment provisions or shorter payment terms, can shift part of the exposure to buyers. Regular reporting on hedge effectiveness, realized margins, and counterparty risk supports governance and enables exporters to refine coverage as demand, rates, and market volatility change.
Which German Export Sectors Face the Most Risk?
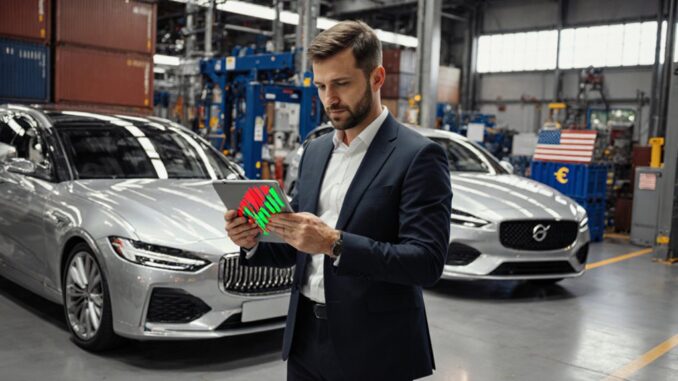
Exchange-rate risk is concentrated in German sectors that combine high non-euro sales exposure, narrow margins, and limited ability to pass currency changes to buyers. Automotive exposure is especially significant because vehicle and component producers sell extensively in the United States, China, and other dollar-linked markets while competing against Japanese, Korean, and US manufacturers. A stronger euro can thus reduce price competitiveness and compress euro-denominated revenues.
Machinery volatility is similarly pronounced. Capital-goods orders are often negotiated months in advance, making invoice values sensitive to currency movements between contract signing and delivery. Small and medium-sized engineering firms may face greater pressure than large groups because export markets account for a high share of turnover and contracts are highly customized.
Chemical, pharmaceutical, electrical equipment, and precision-instrument exporters also carry material risk, though pricing power varies by product specialization. Policymakers should monitor sectoral export concentration, foreign-currency invoicing, and profit-margin trends, since broad euro appreciation can affect employment, investment, and industrial production unevenly across regions.
How Can German Exporters Manage Currency Risk?
The uneven exposure across automotive, machinery, and other export-intensive industries makes currency-risk management a core financial and operational issue for German firms. Exporters can quantify transaction exposure by currency, contract duration, and expected cash-flow timing, then set hedge ratios aligned with budget rates and risk tolerance. Hedging Tools such as Forward Contracts lock in euro values for receivables denominated in dollars, yuan, or sterling, reducing margin volatility and improving planning certainty. Options may preserve upside when exchange-rate movements are uncertain, though premiums require cost-benefit assessment.
Natural Hedging can reduce reliance on financial derivatives by matching foreign-currency revenues with procurement, production, borrowing, or local operating costs in the same currency. Firms can also include Currency Clauses in longer-term supply agreements, triggering price adjustments when exchange rates move beyond negotiated thresholds. Policymakers can support smaller exporters through advisory services, transparent reporting standards, and export-credit instruments. Effective programs require board oversight, counterparty limits, regular stress tests, and consolidated monitoring of exposures across subsidiaries and markets.
The Automotive & Mobility Editorial Team follows one of Germany’s most important industries and its transformation. Coverage ranges from automotive manufacturers and suppliers to electric vehicles, batteries, automotive software, autonomous driving, rail, logistics and new mobility concepts. The team examines both established German mobility companies and the technologies that could shape transportation in the future.